- ssa.govSocial Security
- va.govVeterans Affairs
- cms.govMedicare
- irs.govTaxes
- State & countyProperty tax offices
Named as sources only. USA Handbook is independent and not affiliated with or endorsed by any of them.
Find the chapter that's about you.
Pick your situation, turn to that chapter, and do the one thing at the end of it.
Your husband or wife served in wartime
A wartime veteran who needs help with daily living can receive up to $29,093 a year, tax-free; a surviving spouse up to $18,697. Medical costs come off before your income is tested.
You own your home and you're 65 or older
The exemptions your county won't mention, why the assessment is a guess, and how to appeal with the evidence review boards accept. State-by-state table in the back.
Medicare raised your premium
The surcharge is priced off a tax return from two years ago. If you retired or lost a spouse since, this form asks them to recalculate.
You're deciding when to claim Social Security
The window that sets your check for the rest of your life — and the mistakes that can't be undone once you file.
You recently lost a spouse
The switching strategy for survivors, and the three agencies that each need the same death certificate — in the order to call them.
You're helping a parent
The Drawer File: what to find, where it lives, and what to ask before you ever need it. One afternoon, one folder.
Every chapter ends with one thing to do — usually a single phone call or a single form.
Most people never apply because of a sentence that isn't true.
What people tell themselves, next to what the rule actually says.
The National Council on Aging estimates that more than 9 million older Americans miss out on about $58 billion a year in benefits they qualify for (NCOA, May 2026).
Every number has a source and a date beside it.
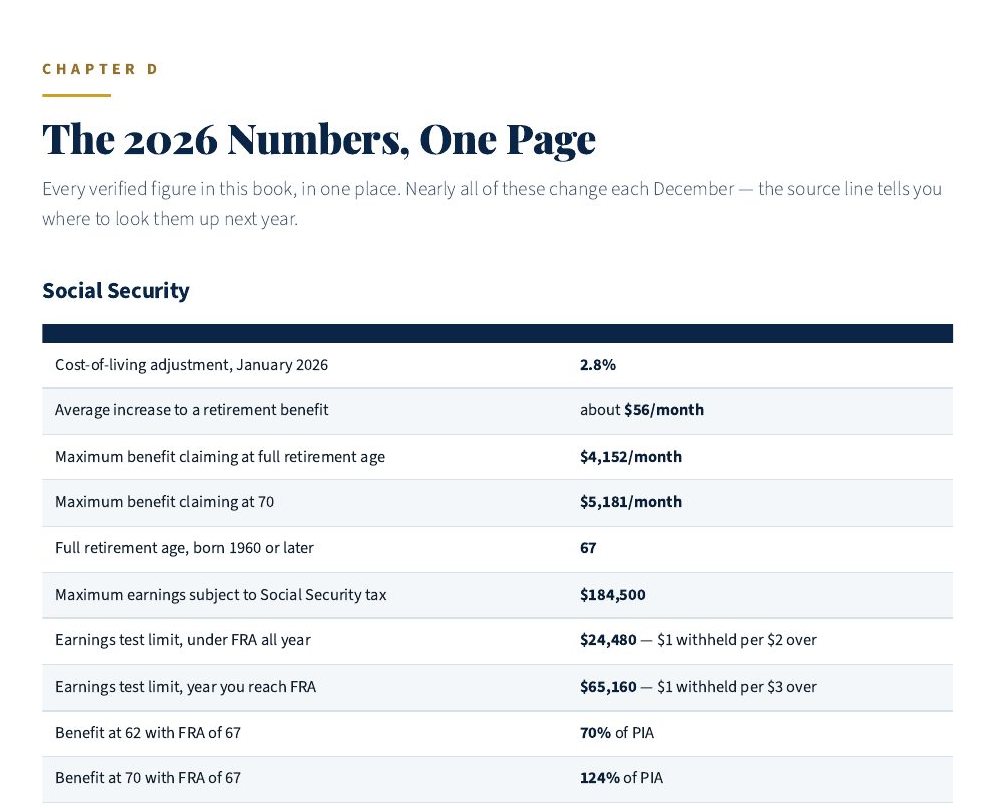
A few of the figures, exactly as the handbook prints them. Most change every December — the source tells you where to look next year.
| Figure | 2026 | Published by |
|---|---|---|
| Social Security | ||
| Cost-of-living adjustment, January 2026 | 2.8% | SSA |
| Maximum benefit, claiming at full retirement age | $4,152/mo | SSA |
| Earnings test limit, under full retirement age all year | $24,480 | SSA |
| Window to correct your earnings record | 3 yrs, 3 mos, 15 days | SSA |
| VA pension with Aid and Attendance · effective Dec 1, 2025 | ||
| Veteran, no dependents | $29,093/yr | VA |
| Veteran with one dependent | $34,488/yr | VA |
| Surviving spouse, no dependents | $18,697/yr | VA |
| Net-worth limit (home and car generally excluded) | $163,699 | VA |
VA figures: Department of Veterans Affairs, Veterans Pension and Survivors Pension rate tables, effective December 1, 2025 through November 30, 2026. Social Security figures: Social Security Administration, 2026.
This is what the pages actually look like.
Real pages from the handbook, not mock-ups.
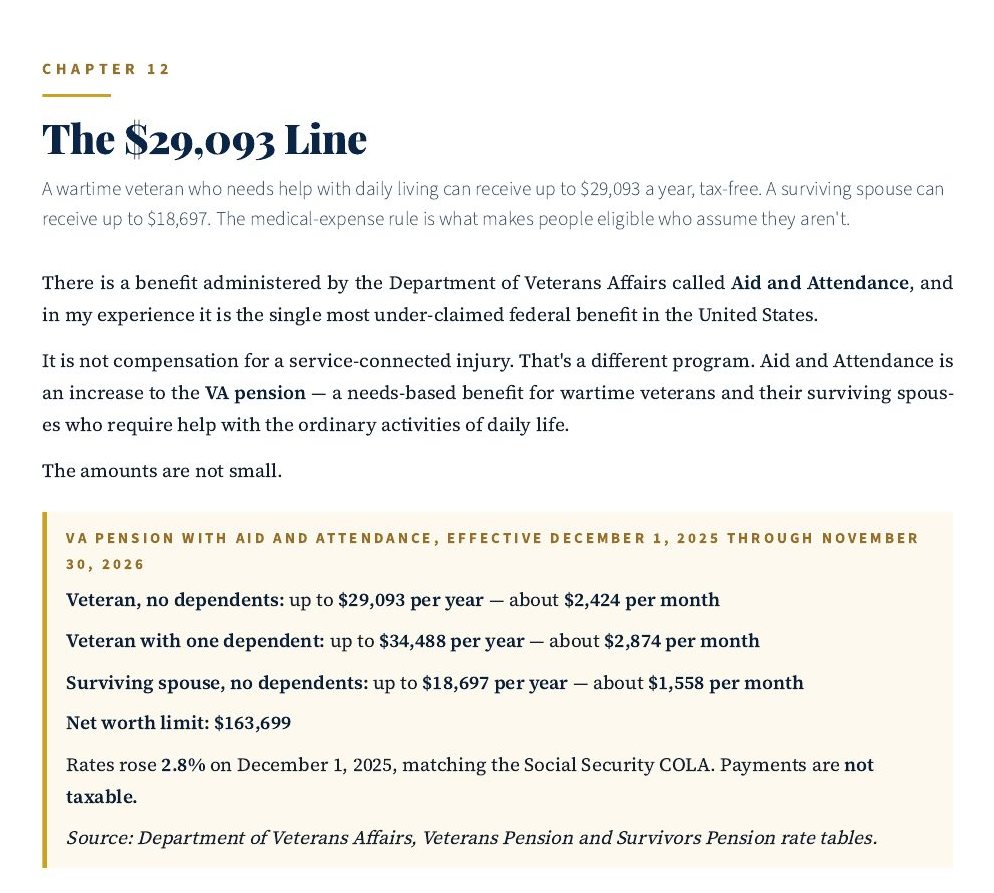
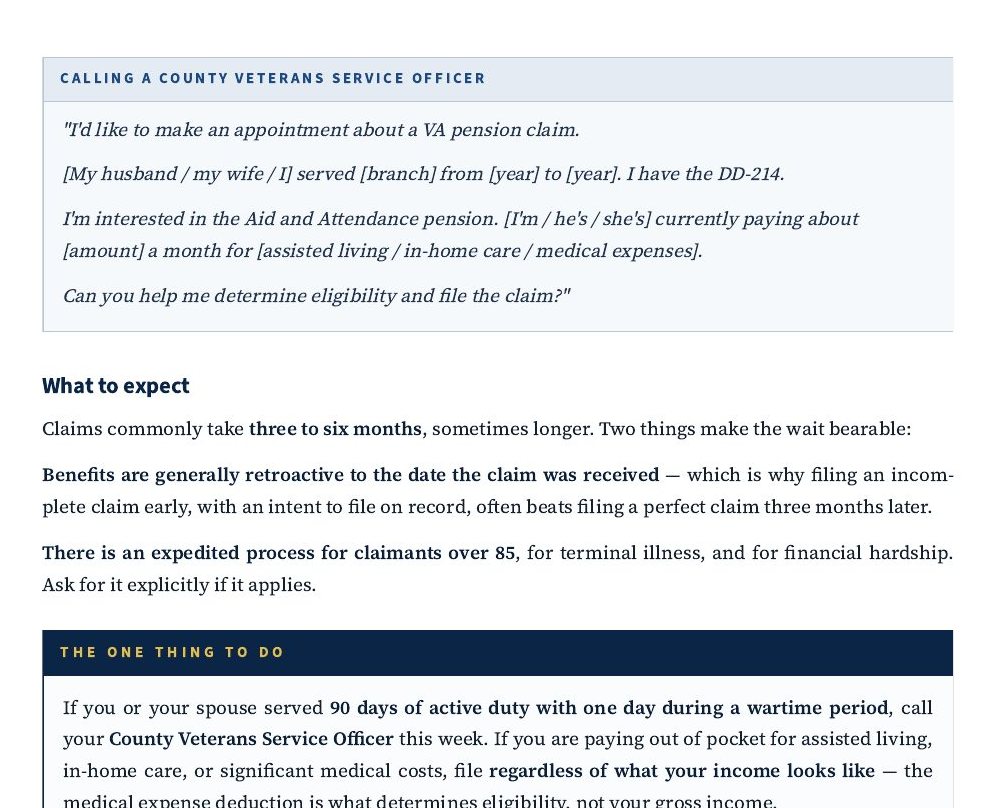
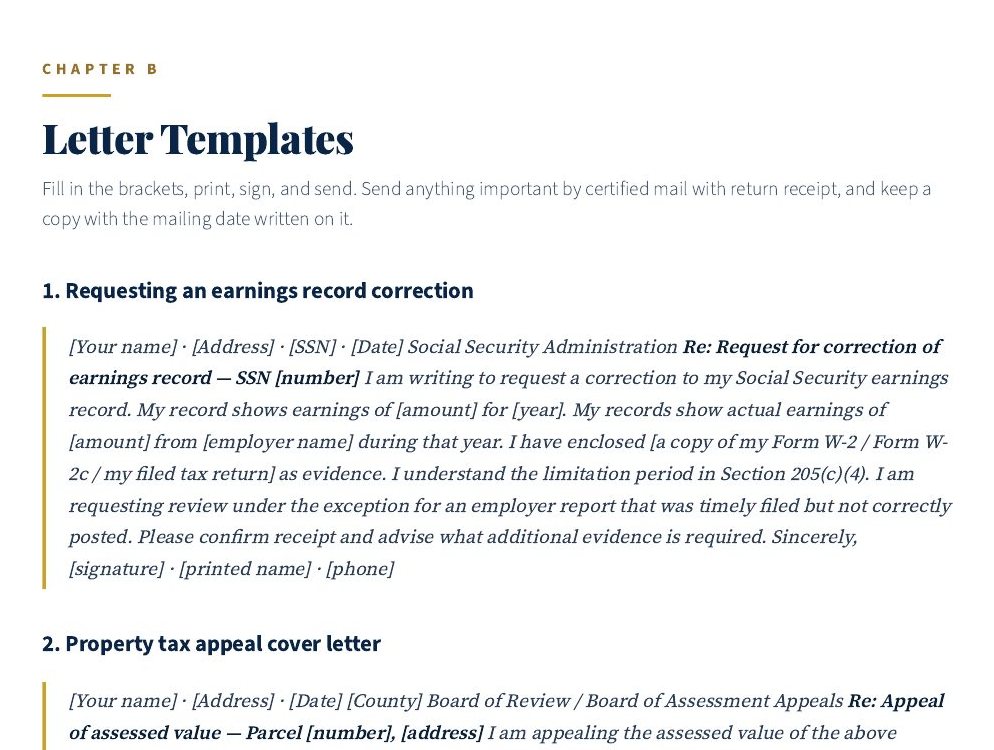
Twenty chapters. One thing to do at the end of each.
Social Security
- The earnings record nobody checksCh. 1
- The eighteen months that decide everythingCh. 2
- Benefits on someone else's recordCh. 3
- The widow's penalty and the switching strategyCh. 4
Your Property Tax Bill
- Five exemptions your county won't mentionCh. 5
- The assessment is a guessCh. 6
- How to appeal, and how to winCh. 7
- The deed nobody checkedCh. 8
Medicare
- The surcharge triggered by one good yearCh. 9
- The enrollment windows that penalize you for lifeCh. 10
- The programs that erase your premiumCh. 11
Veterans and Survivors
- The $29,093 lineCh. 12
- Three agencies, one death certificateCh. 13
The Signatures
- The name on the accountCh. 14
- The power of attorney that isn't limitedCh. 15
- What your will doesn't controlCh. 16
Taxes, the Calendar — and Renters
- The deductions nobody claimsCh. 17
- Deadlines that expire quietlyCh. 18
- What's available if you rentCh. 19
- How to tell a real agency from a fake oneCh. 20
At the backThe Toolkit
- 10 word-for-word phone scripts
- 8 letter templates
- Every form number, indexed
- The 2026 numbers in one place
- Property tax relief by state
- The Drawer File
- A plain-English glossary
What this handbook won't do.
- It won't pretend your state works like every other state. Property tax rules are local. Appendix E tells you which office to call for yours.
- It won't promise you a dollar amount. It shows you the limits, the forms and the people to ask. What you receive depends on your own record.
- It isn't legal or tax advice, and it isn't from the government. It's an independent reference guide. Where the stakes are high, it tells you which professionals will help for free.
- It won't stay current forever. Most figures change every December, so every one is printed with its effective date and the agency to check next year.
Sit down together with one chapter.
Print it — every page is letter size — or open the chapter that matches their situation on a tablet.
Start with the Drawer File in Appendix F: one afternoon, one folder, and the next time something happens, nobody is searching through a shoebox.
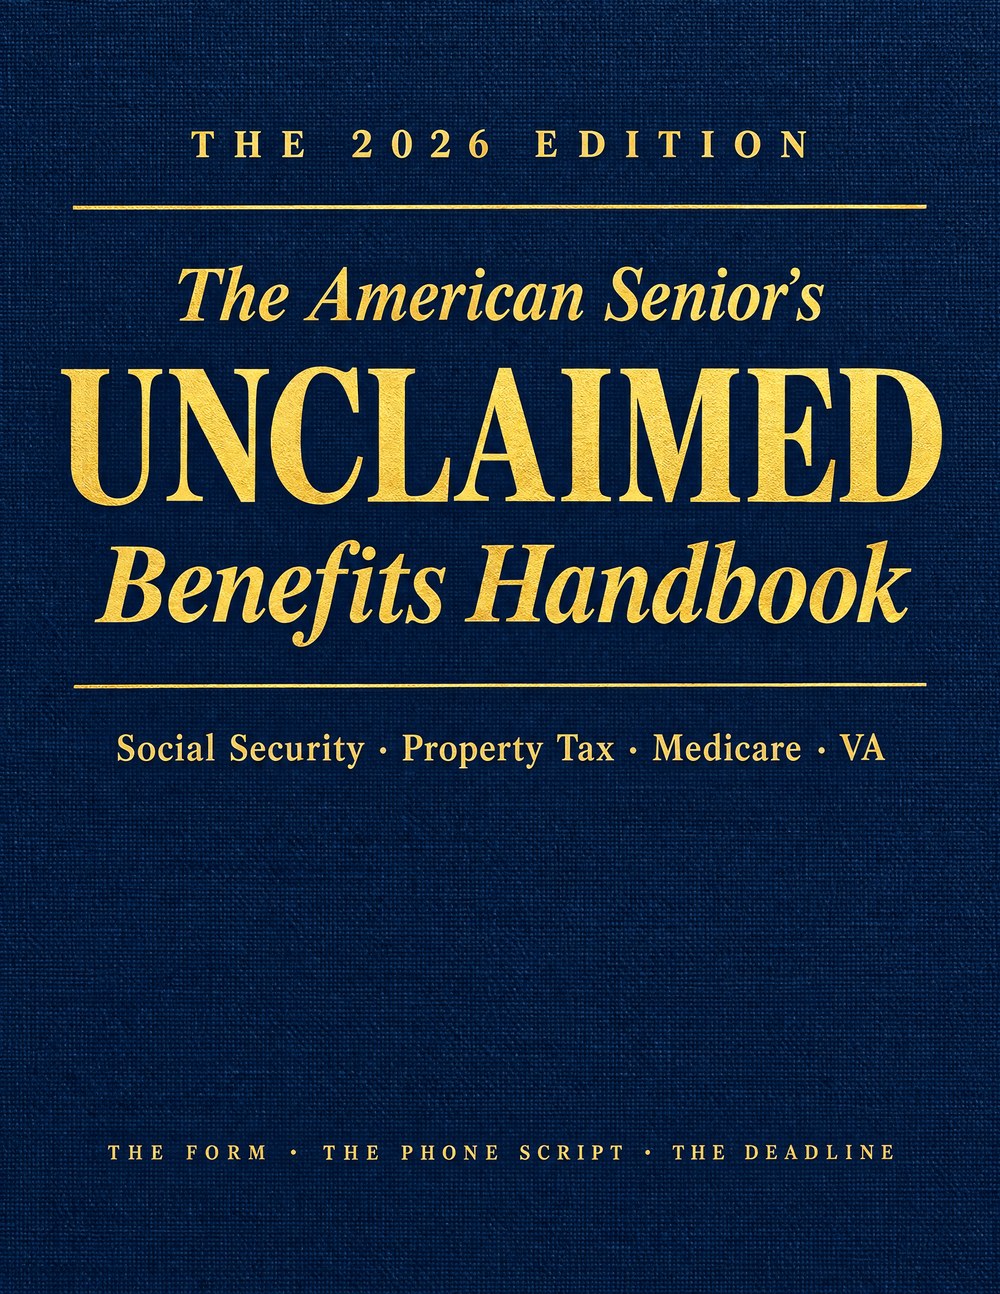
The Handbook, plus two printable files.
$29.99
One payment · No subscription · Yours to keep
Get the Handbook · $29.99Secure checkout by Hotmart · I never see your card
How it works
- Pay once. You'll land on pay.hotmart.com — Hotmart is the payment company. I never see your card.
- Check your email. Your download link arrives within minutes.
- Open the chapter that's about you. On a phone, a tablet, a computer — or print it.
- Do the one thing at the end of it. Usually a single phone call.
Questions people ask first
Isn't all of this free on government websites?
Yes, and that's the point. Every rule in this book is published, most of it in a .gov PDF that nobody reads. It isn't findable, it isn't readable, and no agency's job is to call you about it. What you're paying for is that it has been found, read, dated, sourced and turned into steps.
Is this a government publication?
No. It's an independent guide, not affiliated with or endorsed by Social Security, CMS/Medicare, the VA, the IRS or any government agency. A real agency will never ask you to pay to receive a benefit — Chapter 20 is about exactly how to tell the difference.
I think I make too much to qualify.
That belief is the reason most of this money goes unclaimed, and it's usually wrong. The VA subtracts medical costs before testing your income. Medicare's savings programs exclude your house and a car. The book prints the actual limits so you can check instead of assume.
Will the numbers already be out of date?
Most of them change every December, which is why every figure is printed with its effective date and the agency that published it — so you always know what you're looking at and where to check next year. This is the 2026 edition.
I'm not good with computers or forms.
Almost everything here is a phone call or a paper form. The scripts are written to be read aloud. For VA claims and tax returns, the book points you to people who will do the paperwork with you, free.
There are no reviews. Why should I trust it?
Because it's a new edition and I'd rather show you nothing than something I made up. You can check any figure against the .gov address printed beside it, and you have 7 days to ask for your money back.
How do I know this isn't a scam? Scams aimed at seniors look like this.
That's a fair question, and I'd rather you ask it. Nobody here will call you, ask for your Social Security number or ask for gift cards. You pay once, on pay.hotmart.com — Hotmart is the payment company that handles the sale and refunds, and I never see your card.
Can I buy it for my mother or father?
Yes. Use their email or yours, then forward the PDF or print it for them.
The cost of checking is an afternoon and a phone call.
The cost of not checking can run for the rest of a retirement.
Get the Handbook · $29.997-day money back · Independent guide, not a government agency